
- Key takeaways
- Can you work remotely from France on a visitor permit?
- What the clarification does not solve
- A1 certificates: when can France disregard them?
- What this means for employers posting to or hiring in France
- FAQ


Remote working from France on visitor status is now clearer: in a 23 June 2026 parliamentary response, France’s Interior Ministry confirmed a foreign national working remotely for a foreign employer — paid and taxed abroad, with no link to the French market — can hold “visitor” (VLS-TS visiteur) status. It settles immigration status only; tax, social security and employer risks remain.
Two French developments in mid-2026 matter to anyone with staff working from France for a non-French employer. One clarifies when remote work fits the visitor permit. The other, from the Supreme Court, sets out the narrow circumstances in which France can disregard an A1 certificate issued by another Member State.
Together they define both the opening and the limits for cross-border remote work into France.
Yes — in principle. France’s Interior Ministry confirmed on 23 June 2026 that a foreign national residing in France and working remotely for a foreign employer, with no connection to the French market and still paid and taxed in their home country, can qualify for “visitor” status. Regulated professions are excluded, and consulates and prefectures retain discretion.
The visitor permit (VLS-TS visiteur) has always carried a promise to undertake no professional activity in France, which created years of uncertainty about remote work for a foreign employer. Prompted by written parliamentary question no. 11730 from MP François Gernigon, the Ministry’s response — published in the Journal Officiel on 23 June 2026 — gives the clearest guidance to date.
The Ministry’s logic: business immigration categories are for people who participate in the French labour market and contribute to the French economy. Someone working purely remotely for a foreign employer, unconnected to that market, is treated as “non-active” and fits visitor status rather than a professional permit.
| Scenario | Visitor status likely? |
| Remote work for a foreign employer, paid & taxed abroad, no French clients | Yes, in principle |
| Any work for or benefiting a France-based business | No — needs a work/professional permit |
| Regulated (regulatory) profession activity | Excluded from this analysis |
| Long stay leading to French tax residence | Immigration OK, but tax position changes |
The clarification covers immigration status only. It does not resolve tax residence, social security, employment law, or permanent-establishment (PE) risk for the foreign employer. A person on visitor status for a year who renews may become a French tax resident, shifting where their employment income is taxed.
This is where employers get caught. The Ministry appears to assume the individual stays taxed in their home country — but visitor status can be granted for a year and renewed. Cross the usual residence thresholds, and employment income can become taxable in France instead of at home. Separate questions then follow on social security affiliation and which country’s employment law applies.
For the employer, the sharper risk is a French permanent establishment. An employee habitually working from France can, depending on their role and authority, create a taxable presence for a company that never intended to operate there — with corporate tax and payroll consequences. The pattern we see most is a company approving a “temporary” remote arrangement that quietly becomes permanent, and only later discovering the PE and payroll exposure it created.
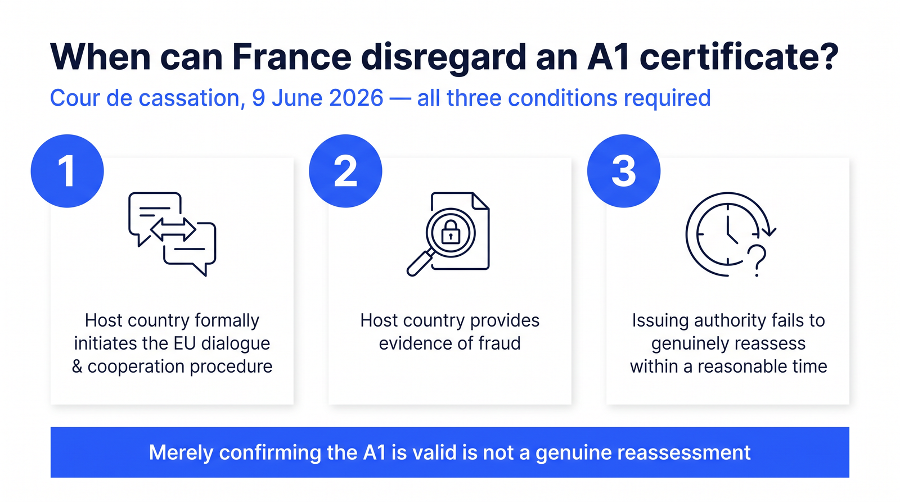
France can disregard an A1 certificate only in narrow circumstances. On 9 June 2026 the French Supreme Court confirmed A1s are binding unless the host country has initiated the EU cooperation procedure, provided evidence of fraud, and the issuing authority has failed to genuinely reassess the certificate within a reasonable time.
The case involved a Spanish company posting workers to agricultural operations in France. After inspections, URSSAF (the French social security collection body) identified signs the A1 certificates may have been obtained fraudulently and asked the Spanish authorities to reassess them.
The French Supreme Criminal Court (Cour de cassation) restated the settled EU position: A1 certificates bind the institutions and courts of the host country until withdrawn or declared invalid by the issuing authority. But it confirmed host-country courts may disregard them where all three of the following are met:
The Court added important guidance on what counts as a genuine review. Under the principle of sincere cooperation, simply confirming that an A1 remains valid is not enough if the issuing authority does not address the specific fraud evidence provided by the host State. In that case, there has been no genuine reassessment — and the exception can apply.
For remote hires on visitor status, confirm the person is genuinely non-active in France — no French clients, employer benefit or regulated activity — and keep evidence of foreign pay and tax.
Track how long remote workers stay: model the point at which French tax residence and social security could shift, and reassess before renewal.
Assess permanent-establishment risk for each remote arrangement, focusing on the employee’s role and any authority to bind the company.
For postings, make sure A1s are genuine and defensible — the certificate protects you only while it stands, and fraud invites the cooperation procedure.
Where an arrangement is really ongoing employment in France, regularise it (for example via portage salarial or French payroll) rather than stretching visitor status.
If a hire is effectively working from France on a lasting basis, Access Financial can regularise it compliantly — running French payroll and social security, engaging independent professionals through portage salarial or an Agent of Record, and helping you manage the permanent-establishment risk — request a free assessment. We can also review posting and A1 arrangements before an inspection does. (In France we provide payroll, portage salarial and self-employed solutions rather than Employer of Record.)
You can work remotely in France on a visitor visa in principle, per the Interior Ministry’s 23 June 2026 guidance, if you work for a foreign employer, are paid and taxed abroad and have no link to the French market. Regulated professions are excluded, and consulates and prefectures still decide case by case.
France can disregard an A1 certificate only where the host authorities have initiated the EU cooperation procedure, provided evidence of fraud, and the issuing authority has failed to genuinely reassess the certificate. The French Supreme Court reaffirmed these conditions on 9 June 2026; otherwise A1s remain binding.
Remote work in France can create a permanent establishment for a foreign employer, depending on the employee’s role and whether they can bind the company. A PE can trigger French corporate tax and payroll obligations, so each lasting remote arrangement should be assessed rather than assumed to be risk-free.
A remote worker on visitor status may become a French tax resident if their stay is long enough or the permit is renewed, at which point employment income can become taxable in France rather than at home. The immigration clarification does not resolve tax residence, which must be assessed separately.
Related articles